
Why Understanding Insurance is a Must for Short-Term Rental Investors

Insurance advertising says the same thing everywhere: “Switch and save.” No one runs an ad that says “Upgrade for better coverage.” When carriers started selling direct online, the industry shifted from coverage to price, and agents selling 100-page contracts often stopped reading past the declarations page. For short-term rental investors, that shift is where most coverage gaps start.
Proper Insurance has insured short-term rentals exclusively since 2014 and has written more than 200,000 policies across all 50 states and Washington, D.C. The pattern that shows up at claim time is rarely a missing policy. It’s an investor holding the wrong contract: one written for a primary home or a long-term tenant, not a short-term rental investment property.
Price is the wrong place to start on a property this exposed to risk. Start with the contract.
TL;DR: Short-term rental investors can insure a property on one of three contracts: Homeowners (HO), Dwelling/Landlord (DP), or Commercial (CP/CL). A Homeowners policy won’t cover an investment property you don’t live in, as American Risk Insurance Co. v. Serpikova shows. A Dwelling/Landlord policy excludes intentional guest damage, caps loss of rents at 12 months, and stops liability at the property line. A Commercial contract is built to close those gaps, so verify which one you carry.
Verify Your Short-Term Rental Insurance
Start by knowing what kind of policy you currently have for your short-term rental property. Start by knowing what kind of policy is on your short-term rental. Hosts are usually sold one of three contracts—a Homeowners (HO) form, a Dwelling/Landlord (DP) form, or a Commercial (CP/CL) form—and only a policy that passes all five criteria of the Short-Term Rental Policy Standard is a short-term rental policy.
- Homeowners insurance (HO) contract
- Dwelling/Landlord insurance (DP) contract
- Commercial insurance (CP/CL) contract
The next thing you have to know when verifying your insurance is to outline what needs to be covered or what needs to be protected:
- The structure and contents inside of it. This is the physical asset and everything you, or your guests, can touch and feel. This includes the building structure, walls, furniture, electronics, etc.
- The revenue or income the asset generates. A short-term rental typically generates a much higher revenue stream for the modern investor than a long-term rental.
- The liability the asset brings with it. This includes the increased risk of bodily injury claims, like slip-and-falls) due to the high-traffic nature of short-term rental properties.
Homeowners Policy with a Home-Sharing Host Activities Endorsement (HO)
Here’s a common scenario – You seek insurance for your investment property that you want to list on Airbnb or Vrbo. The agent provides you with a Homeowners policy (HO) with an endorsement for Airbnb, also known legally as the Home-Sharing Host Activities Endorsement.
Now imagine that years later, a fire occurs at the rental property. However, the insurance carrier denies the claim because you aren’t residing there at the time of the fire, a requirement in Homeowners insurance policies under the definition of “residence premises,” aka the place you live and get your mail.
Legal cases, like American Risk Insurance Company, Inc. v. Veronika Serpikova, highlight similar disputes.
Serpikova’s claim was rejected as her Homeowners policy only covered her primary residence. Despite winning initially in the trial court, the appeals court overturned the decision. She received no claims payment because the insurance contract she signed was clear. This case emphasizes the importance of understanding your insurance coverage’s limitations.
If you own an investment property you don’t live in, and it’s insured under a Homeowners policy, you may have no coverage at all when a claim comes in. The insurance agent sold you the wrong policy, and you purchased it. It’s the insured’s responsibility to read and understand the contract.
Why was I offered a Homeowners policy if it does not cover my investment property?
It usually comes down to training: most agents sell personal-lines forms built for permanent occupants, not for a business that hosts paying guests.
What is the intent of the Home-Sharing Host Activities Amendatory Endorsement?
A Home-Sharing Host Activities Amendatory Endorsement is meant for a primary home (where you live and receive your mail) while being a host or occasionally short-term renting.
Hundreds of thousands of primary Homeowners rent a guest house, a bedroom, or even a tiny home in their backyard on Airbnb or Vrbo. A home-sharing endorsement is Supplemental Host Protection — written for occasional hosting in the home you live in, fine as a supplement but never a substitute. If you regularly rent your primary residence to guests, it needs a short-term rental policy.
Dwelling/Landlord Insurance Contract (DP)
Short-term rentals have a high turnover, with each guest or rental group being entirely different. You willingly hand over the keys to your property and all its belongings to a different group of strangers each week rather than having one tenant for 12 months.
Structure and Contents
Dwelling/Landlord insurance provides no coverage if a group decides to let loose and party all week in your short-term rental and never has. The damage is considered intentional or malicious because you entrusted your property to this group of guests.
Where agents most often get tripped up is the term “vandalism.”
Most comprehensive Dwelling/Landlord insurance contracts cover vandalism, such as the passerby throwing rocks at your windows or spray painting your siding. This differs from the guests that you’ve invited inside your home by giving them the keys.
The average insurance agent sees that “vandalism” is named on the declarations page as coverage but fails to finish reading the length of the contract (as seen below), which clearly states, they do not insure any loss by intentional acts of any tenant.
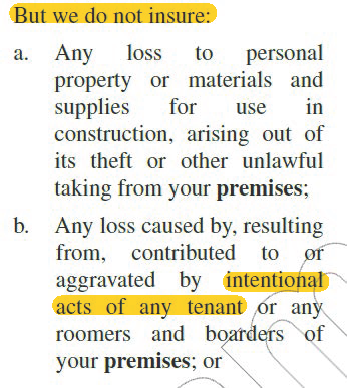
Reference: Sample Dwelling/Landlord Policy (11003 03/06)
Revenue or Income the Asset Generates
Dwelling/Landlord insurance contracts provide “loss of rents,” calculated on “fair rental value,” typically capped at 12 months.
This is problematic for short-term rentals as rental income is typically much higher than a long-term or even mid-term property. At the time of the loss, the carrier will aggregate all surrounding rental properties and determine what’s average or fair based on your property characteristics, such as square footage and bedrooms.
With a short-term rental, the coverage you want is Business Income on an actual-loss-sustained basis — no set time limit; it runs until repairs are complete or your selected limit is reached, whichever comes first. After a total loss such as a fire, a rebuild can take 18–24 months, so choose a limit that reflects that.
For example, in the event of a total loss, such as a fire, it’s typically 18-24 months before your investment property will be fully operational after a rebuild, so more than 12 months of protection is needed. Having no time limit is critical.
Liability of a Short-Term Rental
Short-term rentals are attractive to investors primarily for the nightly rental rates. But with a higher volume of guests comes much higher liability.
You are competing with Hilton and Marriott for travel lodging dollars, which means you are held to the same standard of care, which includes a legal obligation to deliver safe premises to your guests. This all falls under Common Law and, more specifically, Hospitality Law.
Dwelling/Landlord insurance contracts carry “Premise Liability,” which was never intended to cover the scope of a short-term rental business.
If a guest were to get injured off the premise and claim the short-term rental owner liable, there is no protection with a Dwelling/Landlord’s Premise Liability. An easy example of amenities off-premises is if your property offers guests bicycles, canoes, kayaks, etc.
Commercial Contract (CP/CL)
A short-term rental owner should not only carry a Commercial Property (CP) contract but also a Commercial Liability (CL) contract as well, which extends off the premises and provides bodily injury protection for the business operation.
The key in looking at Commercial Liability is reviewing exclusions, as most insurance carriers limit coverage.
Common liability exclusions to look out for and avoid when running a short-term rental business, if possible, are as follows: animal/pet or vicious dog breeds, communicable disease, liquor liability, invasion of privacy, punitive damages, amenities off-premises, assault and battery, nesting or infestation and personal and advertising injury.
Next Steps in Your Short-Term Rental Insurance Journey
Verify your insurance by calling an insurance agent you trust and asking the tough contract questions based on the scenarios outlined in this article. Remember that while an insurance agent can help you understand the contract to their best knowledge of the policy, it is ultimately your responsibility as the property owner to understand the contract you signed.
If a Dwelling/Landlord contract is what’s on your short-term rental today, here are some ways to limit guest-caused damage until it’s replaced.
Five tips to minimize financial losses from tenant/guest-caused damage:
- Screening, screening, and more screening. There is a plethora of short-term rental screening companies that have emerged over the past decade, but property investors are in the business of getting more bookings, not overly screening guests, and denying bookings. The reality is you never know which group will cause significant damage.
- Find a short-term rental damage protection company that provides coverage for both accidental damage and intentional damage. Make sure to read the fine print here, as many providers have the same exclusion as a Dwelling/Landlord policy and only provide accidental damage coverage.
- Charge a significant security deposit, such as $5,000, and take the renter to civil court if damage exceeds it. This is how it’s been handled with long-term rentals for over 100 years.
- Make sure 100% of your bookings are processed through Airbnb, which provides AirCover for Hosts on every booking. But this takes away the option to book directly, which gets away from Airbnb’s high fees. It’s also unclear how responsive Airbnb is to tenant/guest-caused damage – it seems like a bit of a roll of the dice.
- Purchase a short-term rental policy with no sub-limit on damage caused by a guest. It’s the most complete answer, and it costs more because it takes on more risk.
In Summary
- Find an insurance agent you can trust and ask the tough insurance contract questions.
- Home-sharing insurance endorsements or riders only apply to primary homes, not short-term rental investment properties.
- A Dwelling/Landlord contract is long-term rental insurance; on a short-term rental, it leaves you misinsured.
- Upgrade your insurance to a commercial insurance policy that provides coverage specific to a short-term rental investment property.


